Business
6 Stunning new co-working spaces around the globe
Quis autem vel eum iure reprehenderit qui in ea voluptate velit esse quam nihil molestiae consequatur, vel illum qui.

At vero eos et accusamus et iusto odio dignissimos ducimus qui blanditiis praesentium voluptatum deleniti atque corrupti quos dolores et quas molestias excepturi sint occaecati cupiditate non provident, similique sunt in culpa qui officia deserunt mollitia animi, id est laborum et dolorum fuga.
Quis autem vel eum iure reprehenderit qui in ea voluptate velit esse quam nihil molestiae consequatur, vel illum qui dolorem eum fugiat quo voluptas nulla pariatur.
Temporibus autem quibusdam et aut officiis debitis aut rerum necessitatibus saepe eveniet ut et voluptates repudiandae sint et molestiae non recusandae. Itaque earum rerum hic tenetur a sapiente delectus, ut aut reiciendis voluptatibus maiores alias consequatur aut perferendis doloribus asperiores repellat.
Lorem ipsum dolor sit amet, consectetur adipisicing elit, sed do eiusmod tempor incididunt ut labore et dolore magna aliqua. Ut enim ad minim veniam, quis nostrud exercitation ullamco laboris nisi ut aliquip ex ea commodo consequat.
“Duis aute irure dolor in reprehenderit in voluptate velit esse cillum dolore eu fugiat”
Nemo enim ipsam voluptatem quia voluptas sit aspernatur aut odit aut fugit, sed quia consequuntur magni dolores eos qui ratione voluptatem sequi nesciunt.
Et harum quidem rerum facilis est et expedita distinctio. Nam libero tempore, cum soluta nobis est eligendi optio cumque nihil impedit quo minus id quod maxime placeat facere possimus, omnis voluptas assumenda est, omnis dolor repellendus.
Nulla pariatur. Excepteur sint occaecat cupidatat non proident, sunt in culpa qui officia deserunt mollit anim id est laborum.
Sed ut perspiciatis unde omnis iste natus error sit voluptatem accusantium doloremque laudantium, totam rem aperiam, eaque ipsa quae ab illo inventore veritatis et quasi architecto beatae vitae dicta sunt explicabo.
Neque porro quisquam est, qui dolorem ipsum quia dolor sit amet, consectetur, adipisci velit, sed quia non numquam eius modi tempora incidunt ut labore et dolore magnam aliquam quaerat voluptatem. Ut enim ad minima veniam, quis nostrum exercitationem ullam corporis suscipit laboriosam, nisi ut aliquid ex ea commodi consequatur.

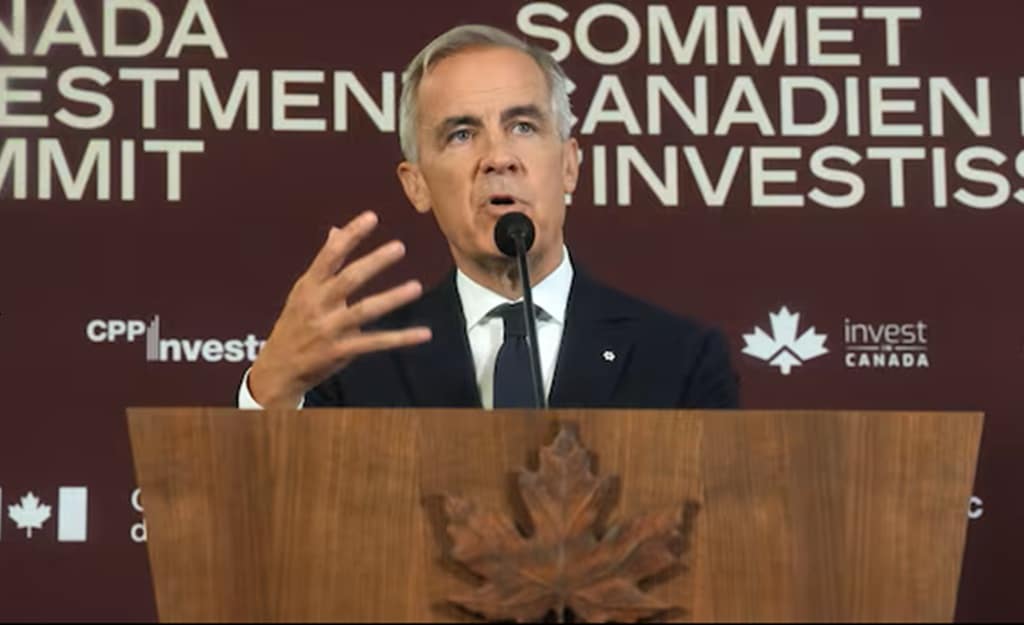
OTTAWA – Mark Carney’s Canada Investment Summit is making headlines with its bold promise to spark a $1-trillion investment boom over the next five years. It sounds like exactly what the Canadian economy needs right now. However, a closer look at what is happening behind the scenes raises some serious questions about the entire operation.
Just weeks before this massive event, a major shakeup occurred at the federal agency in charge of drawing foreign money. The sudden departure of top executives has many wondering who is actually steering the ship. Now, Canadians are demanding more transparency from their government.
Key Takeaways
- Invest in Canada’s CEO abruptly resigned just weeks before the crucial investment summit.
- Nearly half of Canada’s 2025 foreign investment came from buying existing corporate assets.
- Canadians are demanding more transparency on how the $1-trillion goal is actually calculated.
A Sudden Leadership Shakeup Before the Big Event
Less than two weeks before the summit kicked off, Invest in Canada CEO Laurel Broten suddenly left her post. This was a massive surprise move, as her term was not scheduled to end for over a year. Naturally, the timing of her exit has sparked intense speculation in Ottawa. It is highly unusual for a leader to depart right before their biggest event.
Following her unexpected resignation, the government quickly appointed Dominic Barton as the new board chair. However, tough questions remain about the agency’s overall board governance and internal culture. People are also asking how Ottawa’s summit partnership with CPP Investments and PSP Investments actually functions in practice. There seems to be a lack of clarity surrounding these powerful alliances.
These two massive pension funds are acting as heavy-hitting co-hosts for the high-profile Toronto summit. Yet, the specific details of their involvement and decision-making power remain largely out of the public eye. When public pensions are involved in political events, voters expect absolute clarity. Unfortunately, that clarity has been largely missing from the official press releases.
Transparency is absolutely essential when dealing with billions of dollars in public and private capital. Without clear governance structures, it is incredibly difficult to know if the summit will deliver genuine results. Canadians do not want flashy political announcements; they want tangible economic progress. The recent shakeups only fuel skepticism about the government’s true intentions.
Looking Closer at the Foreign Investment Numbers
Beyond the leadership drama, there are very serious concerns about the investment numbers themselves. The government absolutely loves to highlight its recent success in attracting foreign capital. But digging into the latest financial data reveals a slightly different and more complicated story. The reality is not always as bright as the official talking points suggest.
According to recent data, Canada officially recorded $96.8 billion in foreign direct investment inflows in 2025. On the surface, that sounds like a massive victory for the national economy. However, an incredible $43.6 billion of that total came directly through corporate mergers and acquisitions. That means nearly half of the money was spent buying what was already here.
To be completely fair, buying an existing Canadian company is a legitimate form of foreign investment. But it is not necessarily the same thing as building brand new productive capacity. It does not automatically create new factories, innovative infrastructure, or jobs from scratch. Often, it simply means that a foreign entity now owns a Canadian business.
This specific distinction is incredibly important for the long-term future of the Canadian economy. True economic growth relies heavily on building new things and expanding our industrial footprint. We cannot simply rely on trading the ownership of assets that already exist. If we want a stronger nation, we must focus on ground-up development.
What Does Record Investment Actually Mean?
So, what exactly does Ottawa mean when it talks about achieving record foreign investment? Are we seeing a genuine boom in new infrastructure, or just a shuffling of corporate ownership? These are the vital questions that financial journalists and leading economists are now asking. The public deserves honest answers, not just carefully crafted political spin.
The Canada Investment Summit was designed to show the global market that the country is open for business. But broad financial targets and catchy slogans are simply not enough to fix our deeper structural issues. The Canadian economy is currently facing significant productivity challenges that require real solutions. A two-day conference in Toronto cannot magically solve these deeply rooted problems.
With Prime Minister Mark Carney now targeting an astonishing $1 trillion in investment over five years, the stakes have never been higher. This is a massive, historic promise that requires flawless execution and total financial transparency. It also requires a stable bureaucracy that is not plagued by sudden executive resignations. Right now, it is unclear if the government can actually deliver on this bold vision.
Hard-working citizens deserve to know exactly how these ambitious financial numbers are being calculated. They also urgently need to understand how the summit is governed and who is making the crucial decisions behind closed doors. Until the government opens up its books, the skepticism will only continue to grow. A successful economy is always built on a foundation of trust.
The Need for Total Transparency and Accountability
As the investment summit wraps up, the public focus must shift from political promises to hard economic facts. The federal government cannot rely on empty rhetoric if it truly wants to restore faith in its economic management. Leaders must prove that their policies are actually creating wealth for everyday Canadians. Promises of future prosperity mean nothing without measurable results today.
If the $1-trillion goal includes mostly corporate mergers and international buyouts, it may not bring the long-term benefits promised. Canadians need to see investments that build actual value, improve national productivity, and create high-paying jobs. We need new tech hubs, modernized energy grids, and expanded manufacturing facilities. Selling off our current assets to foreign buyers will not achieve these vital goals.
Ultimately, the long-term success of this ambitious initiative depends entirely on clear communication and real accountability. The sudden leadership changes at Invest in Canada only highlight the urgent need for a more stable and transparent approach. When the people in charge are constantly changing, it is hard to build investor confidence. The world is watching how Canada handles this critical moment.
Only time will tell if Mark Carney’s ambitious economic agenda will actually deliver the promised results. Until then, taxpayers have every right to demand clear, honest answers from their government and its financial partners. The future of the Canadian economy is simply too important to be left in the dark. It is time for Ottawa to show us the real numbers.
Trending News:
Poilievre Blasts Carney’s Plan To Sell Off Airports
Food Insecurity and Surging Prices: Canada’s Inflation Squeeze
OTTAWA – Canada has almost every advantage a country could ask for, yet its middle class is becoming poorer relative to the United States, and younger Canadians are reporting some of the lowest levels of happiness in the developed world.
Patrick Boyle, Founder of Palomar Capital, says the problem isn’t a sudden collapse; Canada’s economic stagnation has developed through years of small, defensible decisions that reinforce one another.
The country’s institutions still function, its democracy remains stable, and its natural resources are enormous. However, the arithmetic of ordinary life has stopped balancing for many Canadians. The story begins with the advantages that once made Canada look like the ideal economy.
Canada Once Looked Like the Best of All Worlds
The comparison that seemed absurd in 2012
Canada was once viewed as the perfect combination of a resource-rich Gulf state and a northern European welfare economy. It had vast energy reserves, a social safety net, a highly educated population, and a housing market that appeared to rise every year.
Around 2012, the median Canadian household briefly pulled ahead of its American counterpart by several measures of wealth. At the time, comparing Canada with the United Kingdom’s economic stagnation would have sounded strange. Canada seemed to have avoided many of Britain’s problems.
The explanation was partly a global commodity boom. Crude oil prices had nearly quadrupled over the previous decade, while the Canadian dollar traded at or above parity with the US dollar. High energy prices hurt American consumers, but they boosted Canada’s resource-heavy economy.
That period of outperformance was real, but it depended on conditions that were unlikely to last forever. When commodity prices fell and the currency weakened, Canada’s deeper structural problems became easier to see.
A country built for prosperity
Canada’s natural and institutional advantages remain impressive:
- It has the world’s second-largest land mass.
- It holds the third-largest proven oil reserves and ranks among the leading countries for natural gas.
- It has large supplies of uranium, potash, rare earth minerals, and fresh water.
- Its population is highly educated.
- It has a stable democracy and a strict rule of law.
- It is a member of the G7.
- Its universities and artificial intelligence research centers have produced internationally recognized work.
By any basic measure of national endowment, Canada should be one of the world’s wealthiest countries. The central question is why it has struggled to turn those advantages into stronger productivity, higher wages, and more affordable housing.
The Bank of Canada described the problem as a “productivity emergency.” That phrase captures the nature of Canada’s decline. The country isn’t experiencing an obvious institutional breakdown. Instead, it has allowed economic growth to weaken year after year.
The Numbers Behind Canada’s Slow Decline
Canada’s income per person was roughly 80% of the American level in the decade before the pandemic. Today, it is closer to 70%. That doesn’t mean Canada has suddenly become a poor country. It means the United States has grown faster while Canada has failed to match its progress.
The OECD’s 2025 survey of Canada reaches a similar conclusion, describing Canadian labor productivity as weak compared with peer economies.
A provincial comparison makes the problem more concrete. If Canada’s provinces were treated as US states, the result would look like this:
| Canadian province | Approximate US state ranking |
|---|---|
| Alberta | Around 20th, between Colorado and Tennessee |
| Ontario | Around 48th, below Montana and Alabama |
| New Brunswick | Last, below Mississippi |
The provinces containing most of Canada’s population sit near the bottom of this combined ranking. Alberta’s oil wealth makes it an outlier, while Ontario, the country’s largest and most economically central province, performs far worse than its reputation suggests.
Canada’s social indicators have also deteriorated. The country fell from sixth place in the World Happiness Index to 25th, its lowest ranking since the survey began. That decline happened while Canada remained peaceful, wealthy, and institutionally stable.
Canada’s decline is difficult to recognize because it looks like stagnation rather than a crisis.
The basic issue is the rising cost of a normal middle-class life. Housing, transportation, food, and access to secure work have become harder to manage, especially for people who didn’t buy assets before prices surged.
Protected Industries Have Reduced Competitive Pressure
A sports league becomes less interesting when the same few teams win every year. If new teams face high barriers to entry and the incumbents control the largest stadiums, television deals, and player budgets, the established teams have little reason to improve.
A similar pattern has developed across important parts of Canada’s domestic economy. Large companies operate in markets where regulation, ownership restrictions, and practical barriers make serious competition difficult.
Telecommunications remain highly concentrated
Bell, Rogers, and Telus control roughly 89% of Canada’s wireless subscribers. The result is a mobile market with some of the highest phone bills in the developed world.
A comparable unlimited data plan can cost about twice as much in Canada as in the United Kingdom or France. The Canadian Radio-television and Telecommunications Commission, commonly called the CRTC, has formally allowed new entrants. In practice, regulatory and financial barriers have prevented meaningful competition from developing.
The companies spend heavily on lobbying and regulatory intervention, yet they invest less in network infrastructure per customer than providers in more competitive markets. Consumers pay more while receiving less pressure for lower prices or faster improvements.
Banking favors stability over new growth
Five large Canadian banks hold approximately 90% of the country’s deposits. Canada’s banking system is highly stable, and it avoided the type of financial crisis that affected much of the developed world in 2008.
That achievement matters. Still, stability and dynamism are different things. A concentrated banking sector tends to lend against proven assets. Existing real estate, established corporations, and familiar industries are easier to underwrite than a young company with an uncertain future.
Canadian startups, including those working in artificial intelligence, have often found that American venture capital funds provide more growth-oriented financing than Canadian institutions. The country’s banks protect depositors well, but they aren’t always built to finance the next generation of high-growth businesses.
The same structure appears in airlines, grocery stores, and broadcasting. A small group of large companies earns strong returns from a captive domestic market. Economists call this rent seeking. In Canada, it is more often described as industry stability.
Canada’s Productivity Emergency
Labor productivity measures how much output workers produce per hour. Since 1997, Canadian productivity has fallen progressively behind American productivity. The cumulative gap is now approximately 26 percentage points.
Put simply, for every dollar of output produced by an American worker in one hour, a Canadian worker produces about 74 cents. The issue isn’t that Canadians work dramatically fewer hours. Hours worked per person are broadly comparable between the two countries.
The difference is where investment, talent, and labor are directed. Canada has devoted too many resources to activities that preserve existing wealth and too few to activities that create new products, technologies, and export industries.
Research spending has remained weak
Canada spends less than half the OECD average on research and development as a share of GDP. That gap has persisted for roughly two decades.
A 2025 study on productivity policy found that Canadian labor productivity growth fell from 3.7% annually between 1947 and 1973 to less than 1% per year since 2000. The research on Canada’s long-term productivity decline points to a sustained failure to support productivity-enhancing investment.
A country can have highly educated workers without creating a high-productivity economy. Education helps, but workers also need modern equipment, growing companies, research funding, efficient infrastructure, and access to large markets.
Capital has flowed toward property
Investment in Canada has been directed heavily toward real estate, public administration, retail, and financial services tied to property lending. These sectors can generate income, but they don’t automatically increase the economy’s ability to produce more valuable goods and services.
Public-sector employment grew by approximately 30% between 2015 and 2025. Public servants provide important services, and the point isn’t to dismiss their work. However, government jobs generally don’t produce exportable goods or the type of productivity growth associated with new technology and industrial investment.
The Bank of Canada’s real economic growth forecast is approximately 1.25% annually. That is a weak result for a country with Canada’s resources, population, financial capacity, and access to the American market.
Housing Turned Sitting Still Into a Winning Investment
The average Canadian home sold for about C$237,000 in January 2005. By early 2026, the average price had reached approximately C$661,000, a nominal increase of about 179%.
Inflation doesn’t erase the scale of that increase. In Toronto and Vancouver, property prices rose far faster than incomes, creating a market where owning a home became one of the easiest ways to build wealth and one of the hardest assets for young people to buy.
Housing created wealth without raising productivity
People often say Canadian housing outperformed the stock market. On a simple price appreciation basis, however, the TSX Composite outperformed Canadian housing during the same period. The difference becomes larger when dividends are reinvested.
The important point is the type of return housing produced. A company can rise in value because it creates a product, service, patent, drug, or piece of software. A home usually rises in value because land becomes scarce, planning rules limit supply, or low interest rates increase the amount buyers can borrow.
The building itself hasn’t invented anything or hired a research team. It has remained in the same location while the surrounding market changed.
Housing can create private wealth without creating more national productivity.
Mortgage leverage magnified the gains
Consider a Toronto home purchased in 2005 for C$300,000. A 20% down payment would have required C$60,000. If the property is now worth approximately C$900,000, the owner has gained about C$600,000 in capital appreciation.
That is roughly a 10-to-1 return on the original cash invested. Under Canada’s primary residence rules, the gain is tax-free in the example described.
If the same C$60,000 had gone into a TSX index fund, it would be worth roughly C$195,000 today. That remains a solid result, but taxes would apply to the investment gain.
The incentive was clear. For much of the past two decades, households had a strong reason to buy property early, borrow heavily, and direct savings toward real estate. This was a logical response to the rules of the market.
The wider consequences have been severe. Housing prices in major Canadian cities now equal roughly 12 to 17 times median household income. The national price-to-income ratio is around nine, with Toronto and Vancouver far higher.
The Bank of Mom and Dad
During 2020 and 2021, roughly one-third of first-time buyers received a parental gift to fund a down payment. The average gift was approximately C$82,000. In Vancouver, the average reached C$180,000, while Toronto’s average exceeded C$130,000.
The Bank of Mom and Dad has become one of Canada’s most important mortgage lenders, even though it doesn’t publish accounts.
This arrangement divides younger Canadians into two groups. Some have family assets that can help them enter the market. Others must rely on their income alone while competing against buyers who arrive with six-figure down payments.
The debate over Canada’s housing affordability crisis shows why the problem is political as well as financial. About 66% of Canadian households own their homes, so roughly two-thirds of voters have a direct financial interest in high property values.
A government that built enough housing to restore affordability could reduce the value of existing homes. That makes reform difficult, even when renters and young families face rising costs.
Tax relief for property owners would deepen the imbalance. Treating more tax advantages as the solution to unaffordable housing is similar to giving a patient with high blood pressure more salt. It may produce a reaction, but not a helpful one.
Young Canadians Are Paying for the Old Model
Canada’s overall happiness ranking hides a sharp age divide. Canadians over 60 rank among the world’s ten happiest populations, while Canadians under 25 rank 71st.
Only three countries recorded a steeper fall in youth happiness since 2011: Malawi, Lebanon, and Afghanistan. One has a poverty rate above 70%, one has experienced active armed conflict, and one is governed by the Taliban. Canada is the fourth country in that comparison.
Housing is a major reason for the divide. The median senior family holds approximately C$1.1 million in net assets. A median family whose main earner is under 35 holds about C$159,000.
That gap doesn’t show that young Canadians are less capable or less hardworking. The previous generation bought the asset that produced extraordinary returns. The current generation faces prices that often require a high income, family assistance, or both.
Youth unemployment reached 14.7% in late 2025. About 914,000 young Canadians were classified as not in employment, education, or training. Weak job prospects and high housing costs reinforce one another, making it harder for young people to build assets or feel secure about their future.
Canada’s housing model has created a large transfer of wealth between generations without any formal program announcing that transfer. Planning restrictions, mortgage incentives, primary residence tax treatment, and low interest rates all pushed in the same direction.
Canada Attracts Talent, Then Loses It
Elon Musk offers a recognizable example. Born in South Africa, he moved to Canada at 17 through citizenship connected to his mother. He stayed for roughly two years before moving to the United States.
One person doesn’t prove a national trend, but the broader data points in the same direction. Statistics Canada found that approximately 22,000 to 35,000 Canadians move to the United States each year. About 60% of those applying for US work authorization from Canada weren’t born in Canada. Many were skilled immigrants who came to Canada first.
The median US salary offer for these workers was approximately US$137,000, mainly in computer, mathematical, and engineering fields. Canada attracts highly educated people, and in some cases helps train them. The United States then offers higher pay, a larger technology market, and lower taxes.
The Conference Board of Canada has called this the “leaky bucket” problem. One in five skilled immigrants leaves Canada within 25 years, with the highest rate of departure during the first five years.
Canada’s problem is therefore different from a traditional brain drain. The country has a strong ability to attract and develop talent. Its difficulty is retaining people when they compare Canadian opportunities with American alternatives.
One Customer Buys Most of Canada’s Exports
Approximately 75% of Canada’s exports go to the United States. Merchandise exports to the US equal roughly one-third of Canadian GDP.
The arrangement made sense for decades. Canada shares a border, language, legal traditions, and broad foreign policy interests with the United States. NAFTA and later the USMCA provided a predictable framework for trade.
Canadian businesses had little reason to spend heavily on building access to Asian or European markets when the American market was large, close, and easy to reach. That decision reduced short-term costs, but it left Canada highly exposed to US policy changes.
Recent tariff disputes have made that risk harder to ignore. Coface’s 2025 Canada risk review describes how trade exposure to the United States has weighed on Canadian growth and employment.
Canada’s energy discount
Canada holds the world’s third-largest proven oil reserves, most of them in Alberta’s oil sands. The United States is the dominant buyer, partly because Canada historically lacked enough infrastructure to move oil to tidewater.
Western Canadian Select is a heavy, sour crude that costs more to refine than lighter American benchmark oil. Some discount is justified. However, the historical gap of $15 to $20 per barrel was often larger than the quality difference alone would warrant.
American Midwest refiners benefited from having unusually strong access to Canadian oil. Without alternate customers in Asia or Europe, Canadian producers had limited bargaining power.
The Trans Mountain pipeline expansion entered commercial service in May 2024. It added approximately 590,000 barrels per day of capacity, bringing total capacity to around 890,000 barrels per day.
The WCS-WTI discount narrowed from roughly $19.82 to about $12.52 per barrel after the expansion. That is a meaningful improvement, but the project cost approximately C$34 billion against an original 2012 estimate of C$5.4 billion, an overrun of about 530%.
The project was a major infrastructure management failure. It is also built and gives Canada better access to global buyers.
Energy East was a missed opportunity
Energy East would have carried 1.1 million barrels per day across 4,600 kilometers from Alberta to Saint John, New Brunswick. It could have connected Canadian oil to Atlantic and European markets, as well as Asian buyers.
The Canaport terminal in Saint John had already received C$300 million in upgrades and could accommodate supertankers. Energy East was canceled in October 2017 after years of regulatory review, changing political conditions, and organized opposition.
Some Canadians who examined the project viewed its cancellation as one of the country’s most consequential strategic economic mistakes. The argument is simple: a country with large reserves should have more than one practical customer.
Canada Has Trade Agreements Everywhere Except at Home
Canada has free trade agreements with the United States, Mexico, the European Union, and much of the Asia-Pacific region. Yet the country still lacks a fully functioning internal free trade system.
A British Columbia wine producer may struggle to sell to an Ontario restaurant. An Alberta construction worker may need to requalify before working in Quebec. A medical device approved in one province may require another approval elsewhere.
The International Monetary Fund has compared Canada’s internal trade barriers to a 6.9% tariff on domestic commerce. Estimates suggest that removing these barriers could add between C$90 billion and C$200 billion to annual GDP. Angus Reid polling found that approximately 95% of Canadians support eliminating them.
The reform would allow businesses to sell to larger markets, workers to move more easily, and companies to use existing infrastructure more efficiently. The benefits have been known for decades, but provincial rules and political interests have blocked progress.
Canada’s trade balance is also more complicated than its goods surplus suggests. The country runs a goods trade surplus with the United States, but it has an overall current account deficit once services, tourism, intellectual property, investment income, and financial services are included.
Canada sells raw materials and manufactures less than it buys. In aggregate, it is a net importer rather than a mercantilist economy that systematically accumulates foreign reserves.
Sponsor: Genspark AI Workspace 3.0
The video is sponsored by Genspark AI Workspace 3.0, an all-in-one workspace built around AI agents and cloud-based tools.
Genspark Claw provides each user with a private, always-on cloud computer. According to the sponsor, users can contact Claw through WhatsApp, Telegram, Slack, or Teams for research, email drafts, calls, and other tasks. The finished work is delivered back to the user.
Genspark Workflows automates repetitive tasks across more than 20 apps, including Google Suite, Notion, and Salesforce. Users can select pre-built templates or create custom pipelines.
Genspark Teams adds chat, co-editing, shared projects, documents, slides, design, and video tools in one team hub. New users receive free credits to try premium features, while paid users get unlimited AI chat and AI image access throughout 2026.
Canada Still Has the Capacity to Recover
Canada’s problems are serious, but the country hasn’t run out of assets. It still has natural resources, educated workers, strong universities, financial institutions, and a favorable geographic position.
The country also has eight large pension funds, known collectively as the Maple Eight. Together, they manage approximately C$1.6 trillion. If they were structured as a sovereign wealth fund, they would rank as the third-largest in the world.
That financial capacity could support more investment in infrastructure, technology, and Canadian companies. The issue is whether domestic capital will fund productive businesses or continue flowing mainly into property and established assets.
Canada’s artificial intelligence research base is another genuine strength. Montreal, Toronto, and the Vector Institute form a major research network. Geoffrey Hinton, Yoshua Bengio, and Richard Sutton all did foundational work in Canada and became central figures in modern AI research.
A 2025 survey suggested that around 17 million university-educated people around the world would choose to move to Canada if they could. The country can attract talent. Its challenge is creating enough high-paying, high-productivity opportunities to keep that talent at home.
Canada also has the lowest net debt-to-GDP ratio in the G7, along with a relatively low deficit as a share of the economy. That gives the government more room to invest than many peer countries have.
External Pressure Could Force Reform
Trade tensions have created a stronger political focus on economic self-sufficiency. For much of the past three decades, internal trade barriers and export concentration were polite policy discussions. Now they have become urgent questions.
Canada’s response includes a greater focus on trade diversification, domestic supply chains, pipeline access, and infrastructure. The push to diversify Canadian exports beyond the United States reflects a new awareness that dependence on one market carries a real cost.
The conditions for reform are appearing at the same time:
- External pressure is exposing the risk of relying on one customer.
- Younger voters are less attached to a housing system that benefits existing owners.
- The productivity gap is becoming harder to dismiss.
- Businesses face stronger pressure to compete internationally.
- Skilled immigrants and Canadian-born workers are leaving for better opportunities.
- Internal trade barriers are receiving more public attention.
Canada won’t improve automatically. Its natural resources and fiscal capacity provide the means to change course, but they don’t create the political will by themselves.
The larger warning applies beyond Canada. Developed economies can weaken through protected industries, low research spending, high property prices, internal barriers, and dependence on a single trading partner. Each decision may look reasonable on its own. Together, they can leave a country rich in assets but poor in momentum.
Canada just got there first.
Conclusion
Canada’s economic stagnation is the product of compounding choices rather than one dramatic mistake. Weak competition reduced pressure on major industries, housing rewarded existing owners, low research spending limited productivity growth, and trade dependence left the country vulnerable to decisions made in Washington.
The country still has the resources, talent, capital, and institutions needed to recover. The decisive question is whether Canada will use those advantages to build productive businesses and affordable housing, or continue protecting the arrangements that made earlier generations wealthy.
A gradual decline is easy to ignore because no single day looks catastrophic. Canada shows how a country can remain stable, prosperous, and well-governed while the economic future of its younger citizens becomes harder to afford.
WASHINGTON, D.C. – The United States is shining a bright light on a massive loophole in international trade. For years, companies in China have quietly moved billions of dollars in products through third-party countries to avoid paying steep American tariffs.
Now, the White House is fighting back against what it calls “The Great Transshipment Scam”. This aggressive crackdown targets a sprawling global network designed to trick American customs officials.
The strategy itself is remarkably simple but incredibly costly to the American economy. Products made in China are shipped to another country, given a quick makeover, and then sent to the United States. By changing a label or repackaging a box, these goods suddenly appear to come from Mexico, Vietnam, or Canada. This sleight of hand allows overseas exporters to completely dodge the heavy tariffs designed to protect American industries.
Key Takeaways
- The White House report reveals a $75 billion global network used by Chinese exporters to evade U.S. tariffs.
- This illegal trade practice costs the American government up to $26 billion in lost tariff revenue every single year.
- U.S. Customs and Border Protection is deploying artificial intelligence and steep financial penalties to stop these fraudulent shipments.
When you buy a product that says it was made in Vietnam or Mexico, you expect that to be the whole truth. However, a recent White House report exposes a very different reality playing out in global shipping lanes. Transshipment itself is a normal part of moving goods around our highly connected world. A legitimate product often travels through several different ports before it finally reaches a store shelf in America.
The process crosses the line into illegal territory when the route is used strictly for deception. Chinese exporters ship their completed or nearly completed goods to a middleman country to hide their true origin. Once the cargo arrives in that third country, local workers might simply slap on a new label or repackage the items. The goods are then exported to the United States, falsely claiming the middleman country as their actual place of birth.
This tariff laundering scheme exploded after the United States placed heavy tariffs on Chinese goods in 2018. Instead of losing access to the lucrative American consumer market, many overseas companies simply changed their shipping routes. They built a sprawling system that effectively bypasses the economic barriers erected by Washington. Today, the scope of this hidden network has grown so large that it requires an immediate, government-wide response.
The Staggering Cost to the Economy
The sheer scale of this tariff evasion is difficult to comprehend. The White House bases its latest actions on a central estimate that $75 billion in goods are illegally transshipped annually. This massive flow of disguised products robs the U.S. Treasury of between $19 billion and $26 billion in tax revenue each year. That is money that could otherwise be used to fund domestic programs, build infrastructure, or reduce the national debt.
The financial damage extends far beyond the halls of the Treasury Department. The influx of artificially cheap, tariff-dodging goods creates an unfair playing field for domestic manufacturers trying to compete. According to the government report, this trade scam displaces approximately 450,000 American jobs across various industries. When foreign companies cheat the system, American workers ultimately pay the price on the factory floor.
Furthermore, this illegal activity creates a significant drag on the broader national economy. The White House estimates that the ongoing transshipment crisis reduces the annual U.S. Gross Domestic Product by up to $150 billion. This represents a massive economic wound caused entirely by bad-faith exporters manipulating the rules of global trade. Closing this loophole has become a top priority for trade officials looking to protect American economic interests.
A Global Network of Way Stations
To pull off a scam of this size, Chinese exporters rely on a vast network of international partners. The new report identifies more than 40 different countries that serve as regular way stations for these disguised goods. These nations range from small developing economies to some of America’s closest political allies and largest trading partners. The problem is so widespread that it has infected legitimate trade flows all around the world.
The White House groups these middleman countries into different tiers based on their level of involvement. Tier 1 includes major economies like Canada, Mexico, India, and the European Union. In these large industrial bases, the illegal transshipment of Chinese goods is often hidden within massive streams of perfectly legal trade. Finding the fraudulent shipments among the legitimate cargo is like looking for a needle in a global haystack.
Other nations, particularly in Southeast Asia, have seen their economies deeply intertwined with this practice. Countries like Vietnam, Malaysia, and Thailand are heavily utilized by exporters trying to bypass American tariffs. While leading news sources frequently report on shifts in global supply chains, the line between genuine manufacturing growth and tariff evasion remains blurry. Many legitimate multinational corporations also rely on Chinese parts assembled in Vietnam, complicating the enforcement process even further.
New Penalties and the AI Detective
The United States is no longer relying on simple paperwork checks to stop this massive wave of trade fraud. Customs and Border Protection has intensified its scrutiny and introduced aggressive new penalties to punish violators. If customs agents determine that goods were transshipped specifically to evade tariffs, they apply a massive 40 percent surcharge. This penalty sits on top of the regular tariffs, making the cost of getting caught incredibly high for importers.
To enforce these rules, the government is turning to advanced technology. The White House announced the deployment of a new artificial intelligence system appropriately named “Detective Border”. This powerful software uses complex data analytics to track supply chain movements and flag suspicious shipping patterns in real time. The AI never sleeps, constantly reviewing shipping manifests to ensure accurate labeling and catch tariff evaders.
The crackdown focuses heavily on a legal concept known as “substantial transformation.” For a product to legally claim a new country of origin, it must undergo significant manufacturing in that second country. Simply screwing two pieces of wood together or placing a finished phone in a new box does not pass the test. Customs officers now rigorously evaluate the actual value added during the intermediate stop before allowing goods into the country.
What This Means for Supply Chains
This aggressive enforcement strategy is sending shockwaves through the global shipping and manufacturing industries. Importers can no longer rely on superficial origin labels to breeze through American customs checkpoints. The current climate demands rigorous documentation, transparent supply chains, and a deep understanding of complex trade laws. Companies that fail to adapt face severe financial penalties and the potential seizure of their valuable merchandise.
The impact will be felt by many well-known multinational brands that operate factories overseas. Companies that build electronics, clothing, and consumer goods often source raw materials from China before final assembly elsewhere. These businesses must now prove exactly how much work was done in the secondary country to avoid the dreaded transshipment label. The burden of proof has shifted entirely onto the importer, slowing down supply chains and increasing compliance costs.
Additionally, the government is closing a popular loophole for low-value packages entering the country. In the past, companies could route goods from China through a third country and break them into tiny, duty-free shipments. With new rules removing these exemptions for Chinese-origin goods, every single parcel now faces formal customs entry. This change blocks a major avenue used by overseas sellers to flood the American market with cheap, untaxed products.
Looking Ahead in the Trade War
The release of the White House report marks a significant escalation in the ongoing economic battle between Washington and Beijing. It arrives during a tense period for international relations, shortly before anticipated diplomatic meetings between the two superpowers. The United States is sending a clear message that it will no longer tolerate the systematic abuse of its trade policies. American leaders want to ensure that the economic benefits of their tariffs actually protect domestic industries as intended.
Other nations caught in the middle must also navigate this new, stricter reality carefully. Countries like Mexico and Vietnam face intense pressure to monitor their own ports and prevent Chinese companies from exploiting their borders. They must balance their vital trade relationships with the United States against their deep economic ties to China. The days of looking the other way while millions of boxes quietly change labels appear to be over.
Ultimately, this crackdown aims to restore fairness to the American market and protect local manufacturing jobs. By dismantling the “Great Transshipment Scam,” the government hopes to recover billions of dollars in lost revenue. It is a massive undertaking that requires cutting-edge technology, aggressive penalties, and constant vigilance at every port of entry. The global supply chain is being rewired in real time, and American customs agents are leading the charge.
Trending News:
JD Vance Warns California and Other Blue States Over Medicaid Fraud
Canada’s $10 Billion Trade Move: Carney’s Bold Plan to Break Free from US Reliance
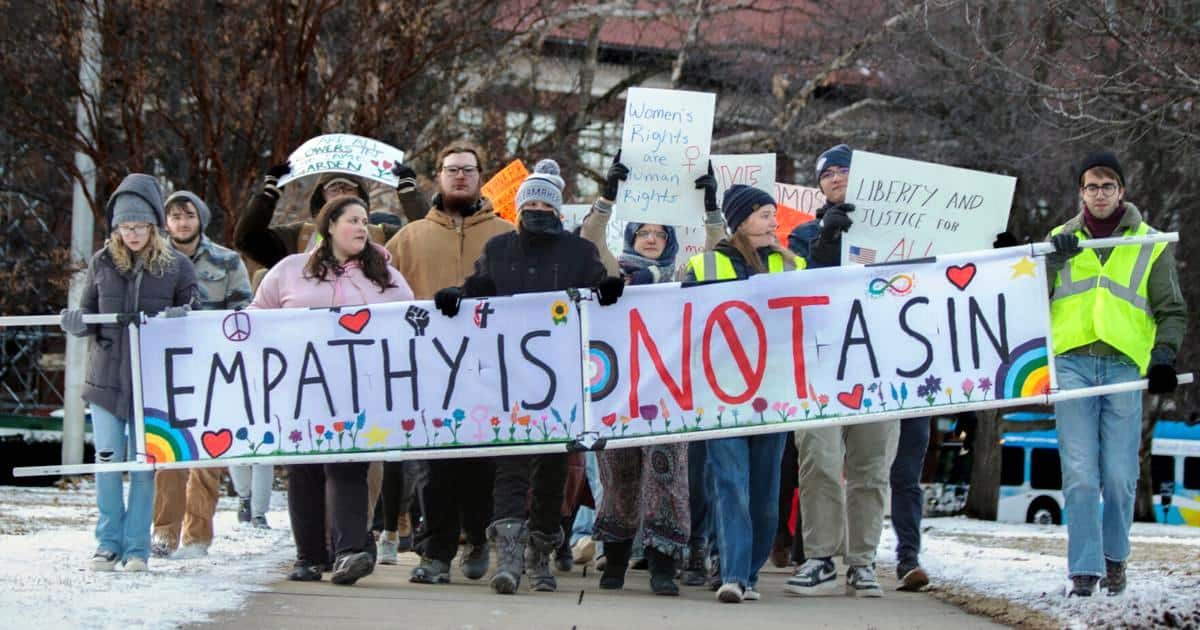
Is Modern Political Empathy Actually Just Hidden Narcissism?
US Trade Moves Put Massive Pressure on Canada
Canada Sheds 68,000 Jobs As Economic Fears Deepen
Pierre Poilievre Critiques Reporter Who Questions His Leadership
How Canada’s Combating Hate Act Stifles Free Speech
Uncovering the Truth Behind Inequality: A Bold New Vision
How Progressivism Replaced Religion With A New Secular Faith
Behind Carney’s $1-Trillion Canada Investment Scheme
Poilievre Blasts Carney’s Plan To Sell Off Airports
Food Insecurity and Surging Prices: Canada’s Inflation Squeeze
Uncovering the Truth Behind Inequality: A Bold New Vision
How Progressivism Replaced Religion With A New Secular Faith
Canada Sheds 68,000 Jobs As Economic Fears Deepen
Food Insecurity and Surging Prices: Canada’s Inflation Squeeze
Poilievre Blasts Carney’s Plan To Sell Off Airports
Behind Carney’s $1-Trillion Canada Investment Scheme
How Canada’s Combating Hate Act Stifles Free Speech
Pierre Poilievre Critiques Reporter Who Questions His Leadership
US Trade Moves Put Massive Pressure on Canada
Is Modern Political Empathy Actually Just Hidden Narcissism?

Jimmy Kimmel Slammed for “Vile” Melania Trump “Expectant Widow” Joke

President Trump Addresses Nation on War with Iran

Trump Warns NATO Allies: America Won’t Protect Slackers After Iran Clash

Senate Hearing on Fraud and Foreign Influence Turns Tense Over Minnesota Scandals

CNN Forced to Backtrack Its Reporting on Trump’s Iran Talks

Joe Rogan Slams Gavin Newsom for Mocking Nick Shirley

Mosque Set Ablaze in Iran a Citizens Revolt Against the Islamic Regime

AOC Accuses Jessie Watters of Fox News of Sexualizing and Harassing Her

JD Vance Exposes Walz’s Fraud and CNN’s Lies in White House Presser

Milestone Card Credit: How the Milestone MasterCard Can Transform Credit
-

 News9 months ago
China-Based Billionaire Singham Allegedly Funding America’s Radical Left
-
Crime10 months ago
YouTuber Nick Shirley Exposes BILLIONS of Somali Fraud, Video Goes VIRAL
-
Politics10 months ago
Ilhan Omar Faces Renewed Firestorm Over Resurfaced Video
-
Politics9 months ago
2026 Midterms Guide: Candidates, Key Issues, and Battleground States
-
Politics8 months ago
CNN Delivers Stark Reality Check to Democrats Over Voter ID
-
Politics8 months ago
Ilhan Omar’s Connections to Convicted Somali Fraudsters Surface
-
Politics7 months ago
Rep. Ilhan Omar Faces Heat as Minnesota Voters Seek Change
-
Politics8 months ago
Trump Approval Rating (February 2026 Poll Results, Approve vs Disapprove)